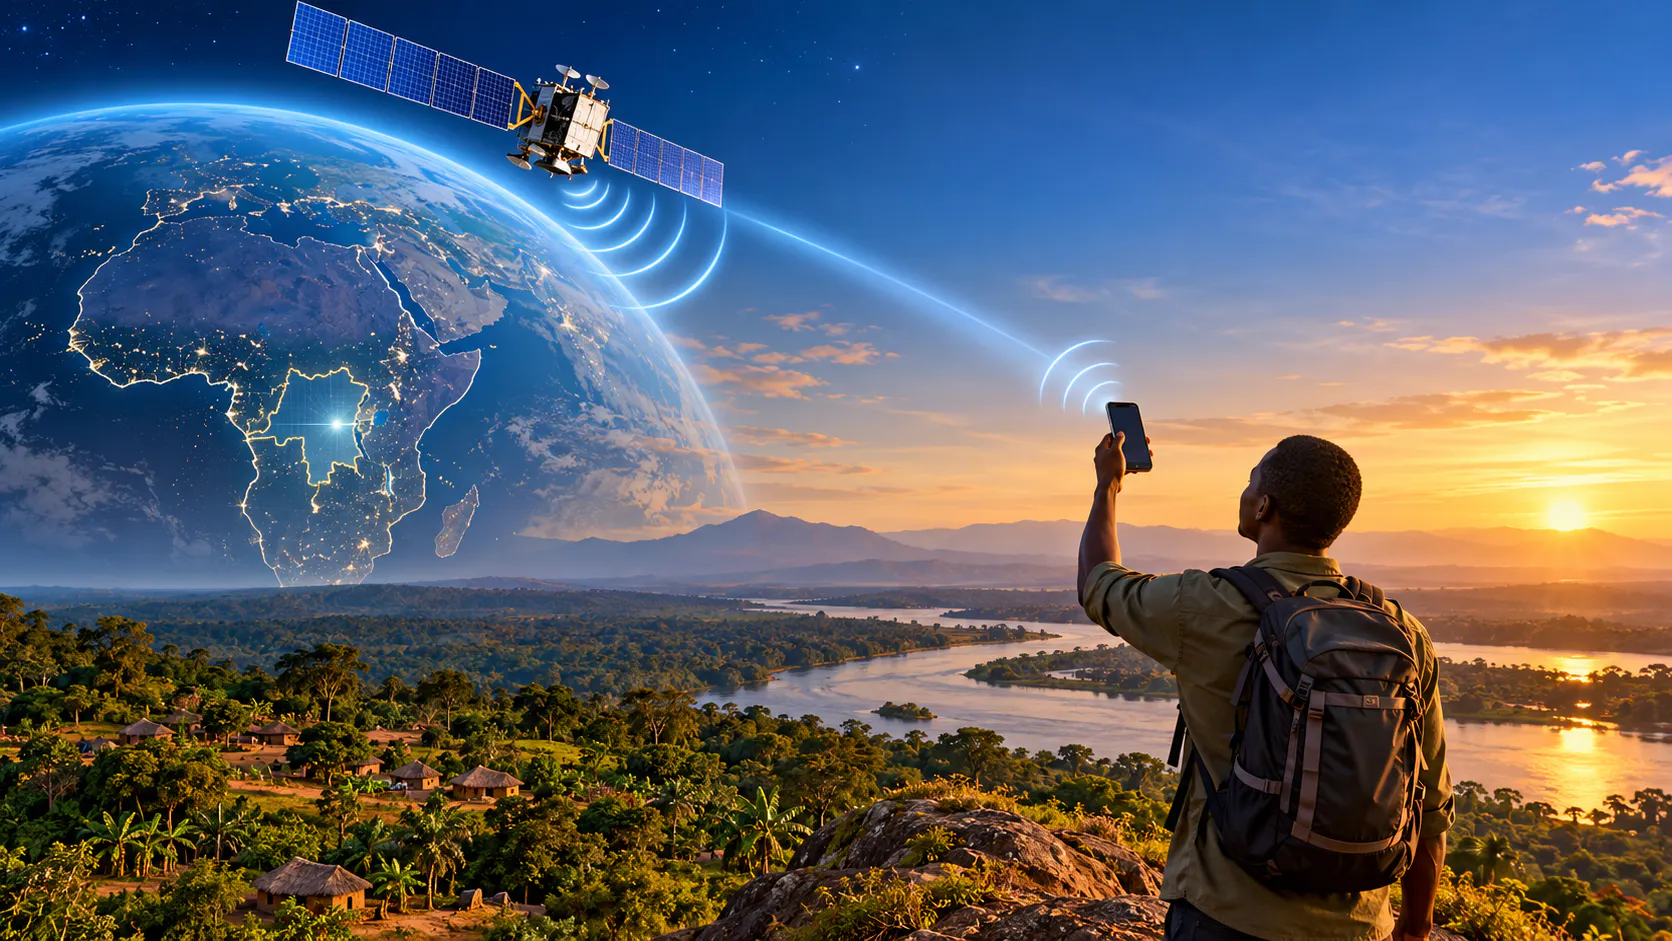
A mobile signal no longer has to come from a tower on the ground. On 14 August 2026, Airtel Africa and Starlink launched a commercial satellite-to-mobile service in the Democratic Republic of the Congo (DRC), the first deployment of Starlink Mobile of its kind in Africa. Customers with compatible smartphones can access selected services in areas outside terrestrial network coverage, provided they have a clear view of the sky. The initial offering supports SMS and light-data applications, including WhatsApp messaging, without requiring a satellite dish or separate terminal, with the launch marking a change in how mobile coverage can be extended. Conventional networks depend on a physical chain of towers, backhaul links, power systems and other infrastructure, while satellite direct-to-cell technology adds another layer: satellites equipped to communicate with ordinary compatible smartphones can provide connectivity where terrestrial coverage is absent. For a country as geographically extensive as the DRC, where reaching remote communities with conventional infrastructure presents practical and economic challenges, that additional layer has potential value. It does not, however, mean that every location will receive continuous service or that satellite connectivity can immediately deliver the full capabilities of a terrestrial broadband network.
On the commercial front, Airtel brings its existing customer relationships and local market presence in complement to Starlink's satellite system. Their partnership, announced in December 2025, envisaged the introduction of direct-to-cell connectivity across Airtel Africa’s 14 markets during 2026, subject to country-specific regulatory approvals. The DRC has become the first market to move from testing to commercial deployment, following successful data and messaging trials in Kenya earlier in the year. The experience gained there may inform subsequent rollouts, although each national market will have its own regulatory and operational requirements.
As a result, this model changes the investment question facing telecommunications operators. Extending terrestrial networks into sparsely populated areas can require substantial capital expenditure before subscriber revenues justify the cost. Satellite connectivity offers another means of reaching some of those users without constructing a mobile tower at every location. It also gives satellite operators access to customers through established telecommunications providers, rather than requiring them to build an entirely separate retail relationship with every mobile subscriber. The partnership distributes the work across two systems, each contributing infrastructure and commercial capabilities that the other does not necessarily possess. There are however limits to what the DRC launch currently provides. The initial service is designed for basic communications and selected low-data applications, not unrestricted high-speed internet, video streaming or a complete substitute for conventional mobile broadband. Access also depends on device compatibility, sky visibility, service availability and the applicable customer plan.Satellite-to-mobile connectivity should therefore be understood as a complement to terrestrial networks, particularly in coverage gaps, while the economics and technical performance of broader services continue to develop.
As satellite operators begin to extend mobile coverage through partnerships with established telecommunications providers, their ability to scale commercially depends in part on how these services fit within national and international regulatory frameworks. Direct-to-cell services must operate within national telecommunications frameworks, including applicable spectrum permissions and regulatory requirements. International coordination through the International Telecommunication Union provides a framework for managing radio-frequency use and satellite systems across borders, but commercial availability in one country does not automatically confer permission to operate in another. Airtel Africa has explicitly made the expansion of its partnership conditional on the relevant national approvals. The pace of deployment will consequently depend not only on satellite capacity and handset compatibility, but also on the decisions of national regulators. That regulatory role matters for African governments considering how satellite connectivity fits within their own digital-development priorities. A partnership with a global satellite operator may extend coverage more quickly than building terrestrial infrastructure in every underserved location, but governments still have to consider service quality, consumer protection, competition, emergency communications, data governance and the terms under which local operators and international providers cooperate. The commercial launch itself does not establish how these questions will be resolved across Airtel Africa’s wider footprint.
There is also a distinction between extending coverage and achieving meaningful connectivity. A signal can allow a person to send a message from an area previously outside the network, but the benefits depend on affordability, device access, reliable service, and the applications that can actually be used. Basic messaging may be valuable for people travelling through remote areas, communities separated from existing coverage and workers whose activities take them beyond conventional network range. It cannot by itself resolve the broader barriers to digital participation. Therefore, and in conclusion, Airtel and Starlink’s DRC deployment places Africa within the development of a new telecommunications architecture. The mobile network remains on the ground, but its reach can now be supplemented from orbit. Whether this becomes a durable tool for closing coverage gaps will depend on how well the technology integrates with existing networks, how national regulators authorise it and whether the resulting service meets the needs of the people it is meant to connect.